Paths to Ownership › Renters Ready to Buy
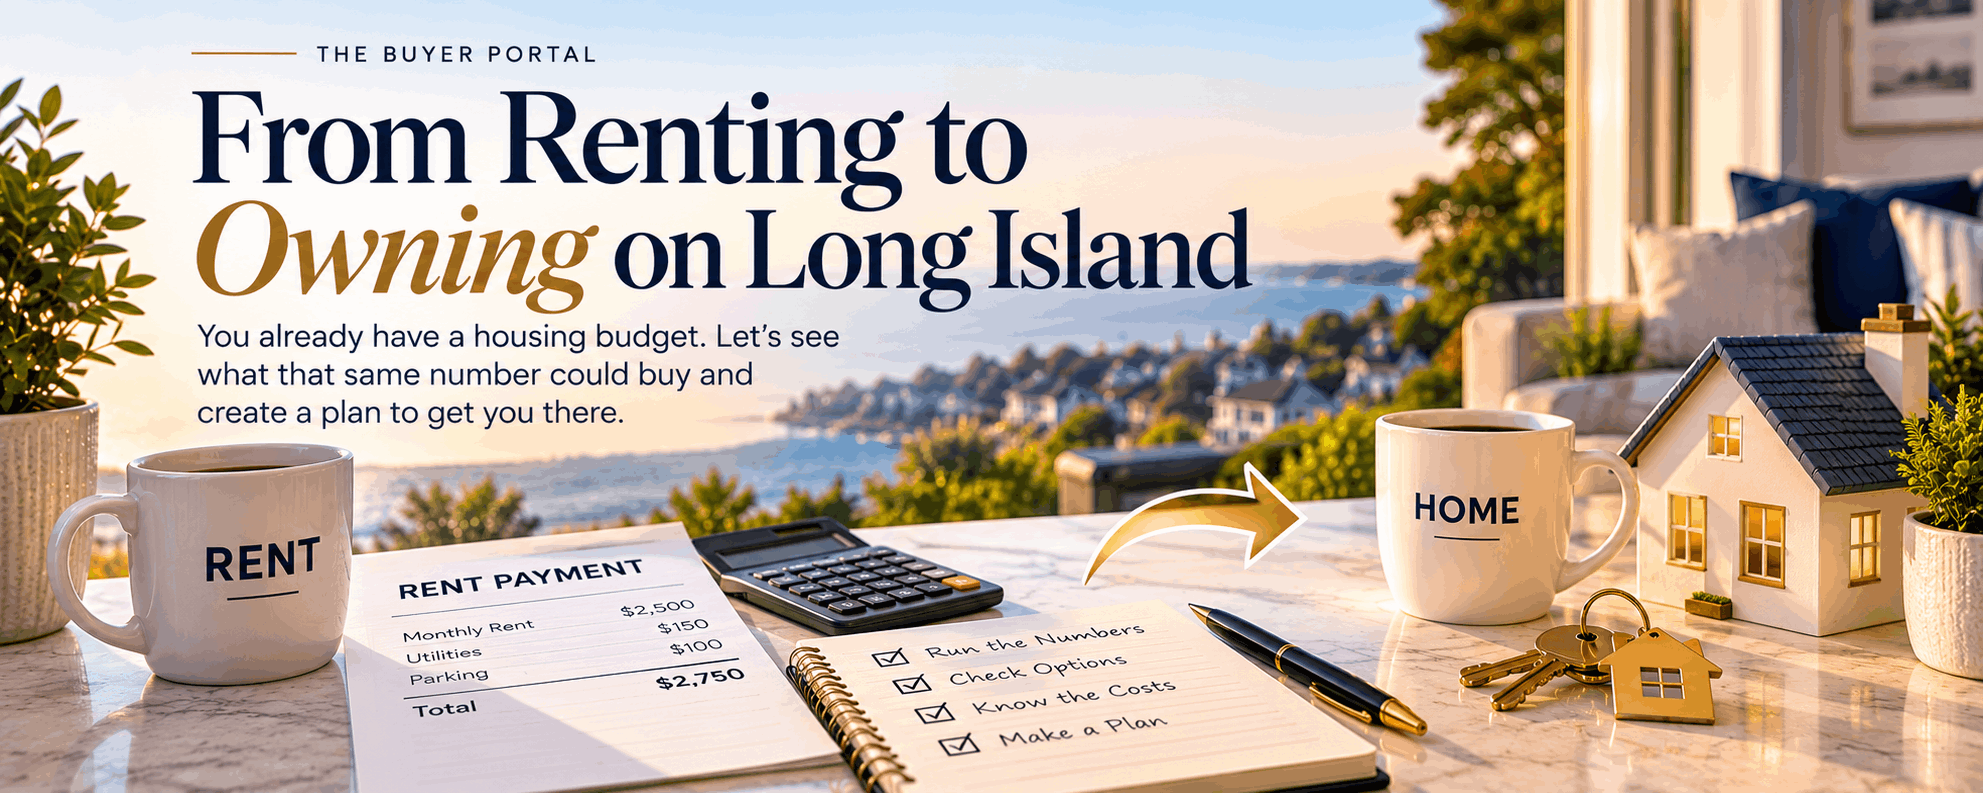
Path 1 · Renters Ready to Buy
From Renting to Owning on Long Island & Queens
You already have a housing budget. You send it to your landlord every month. The real question is what that same number could buy, what it takes to get there, and whether now is the right time or next year is.
- ◆Start with the number you already pay. Rent Check turns your rent into a purchase price in about a minute.
- ◆Honest about timing. If the right move is renting one more year and saving, we will tell you.
- ◆A partner on every file. More than one person always knows where your search stands.
Why Start With Rent
Your Rent Is Already a Mortgage-Sized Payment.
Most renters start the buying conversation with "what are rates doing?" That's the wrong first question. The better one is "what does my rent buy?"
Here's why. When a lender looks at a home purchase, they look at the whole monthly housing payment: principal and interest, property taxes, homeowners insurance, mortgage insurance if you put less than 20% down, and any maintenance or common charges. If your rent already covers a payment that size, you've been proving you can carry it for years.
You already have a housing budget. You're just sending it to someone else.
What usually stands in the way isn't the monthly payment. It's the cash: the down payment, closing costs, and a cushion in the bank after you close. That's the part we help you plan for, one piece at a time.
And sometimes the honest answer is that renting a little longer makes more sense. You'll hear that from us too.
The Calculator
Rent Check: What Your Rent Could Buy
Type in what you pay each month. Rent Check treats it as your whole housing budget and works backward to a purchase price, then shows you three things:
A purchase price
What your rent covers as a full monthly payment, taxes and insurance included.
Five years, side by side
What five years of renting costs next to five years of owning, and the equity on the owning side.
Cash to close
The number most renters actually need to plan for.
It runs the numbers for a house, a condo and a co-op separately, because in New York they don't cost the same way.
Run Rent CheckSame Rent, Three Different Homes
House, Condo or Co-op: Where Your Payment Goes
A $3,000 budget doesn't go the same distance in every kind of home, because each one splits the monthly bill differently.
House
You pay property taxes directly, usually through your mortgage payment, plus insurance. Repairs and upkeep are all yours, so budget for them on top of the payment.
Condo
You own your unit and pay its property taxes yourself. Common charges cover the building and grounds, but not your unit’s taxes.
Co-op
You own shares in the building. Monthly maintenance usually includes your share of the building’s property taxes, which is why a co-op maintenance number can look high next to condo common charges.
How co-ops and condos work →The Road From Renting to Owning
Five Steps, in Order
Step 01
Run your number
Start with Rent Check so you know the price range your rent supports before you look at a single listing.
Step 02
Know your cash
Down payment, closing costs and money left in the bank after closing. Twenty percent down isn’t the requirement most renters think it is.
Step 03
Talk to a lender
Only a lender can pre-approve you. We can introduce you to lenders who work on Long Island and in Queens every day.
Step 04
Line it up with your lease
Work backward from your lease end date so you aren’t paying rent and a mortgage longer than you have to.
Step 05
Shop, sign, close
In New York, attorneys draft the contract and your accepted offer isn’t binding until both sides sign. We walk you through every step.
Twenty percent down is a mortgage insurance threshold, not a rule. Plenty of buyers put down less. Read how the 20% down myth works →
Keep Going
From the Rent Series
What Renters Ask Us
Questions About Going From Renting to Owning
Does paying rent on time help me get a mortgage?
It can. Some loan programs can count a record of on-time rent payments, which matters most if your credit history is thin. Ask your lender whether theirs does, and keep your payment records handy either way.
How much do I need saved besides the down payment?
Plan for closing costs, which in New York include attorney fees, title insurance and lender fees, plus some money left in the bank after closing. Co-op boards often set their own minimum for that cushion. Rent Check shows an estimated cash to close number for your price range.
When should I start looking before my lease ends?
Start with the numbers and a lender conversation well before your renewal notice shows up. From accepted offer to closing usually takes weeks to a few months, depending on the loan and, for co-ops, the board.
Can I break my lease to buy a home in New York?
It depends on your lease. New York law requires landlords to make a reasonable effort to re-rent a unit when a tenant leaves early, which can limit what you owe. Read your lease first and talk to an attorney before you give notice.
Is Rent Check a pre-approval?
No. It’s a planning tool. Integrity Core Realty is a brokerage, not a lender, and only a lender can pre-approve you for a loan.
Whenever You’re Ready
Find Out What Your Rent Can Buy
One conversation. We go over your Rent Check numbers, your cash and your timing. No contract, no pressure.
Start a ConversationCall (516) 200-1202How Integrity Core Realty Can Help You
Selling during a life transition? Our team handles that too.
Speak With Our Team
Tell Us About Your Rent.
Fill out the form below and we’ll reply within one business day. Share what you pay now and when your lease is up, and we’ll take it from there.